Half a Million In, $7,097 Out. Is Your Agency a Business or a Job?
The short version
- Private bail agencies never have to publish their books. One small Denver company did, because it had registered with the SEC. In 2013 it took in $512,710 and kept $7,097, about 1.4 cents of every dollar.
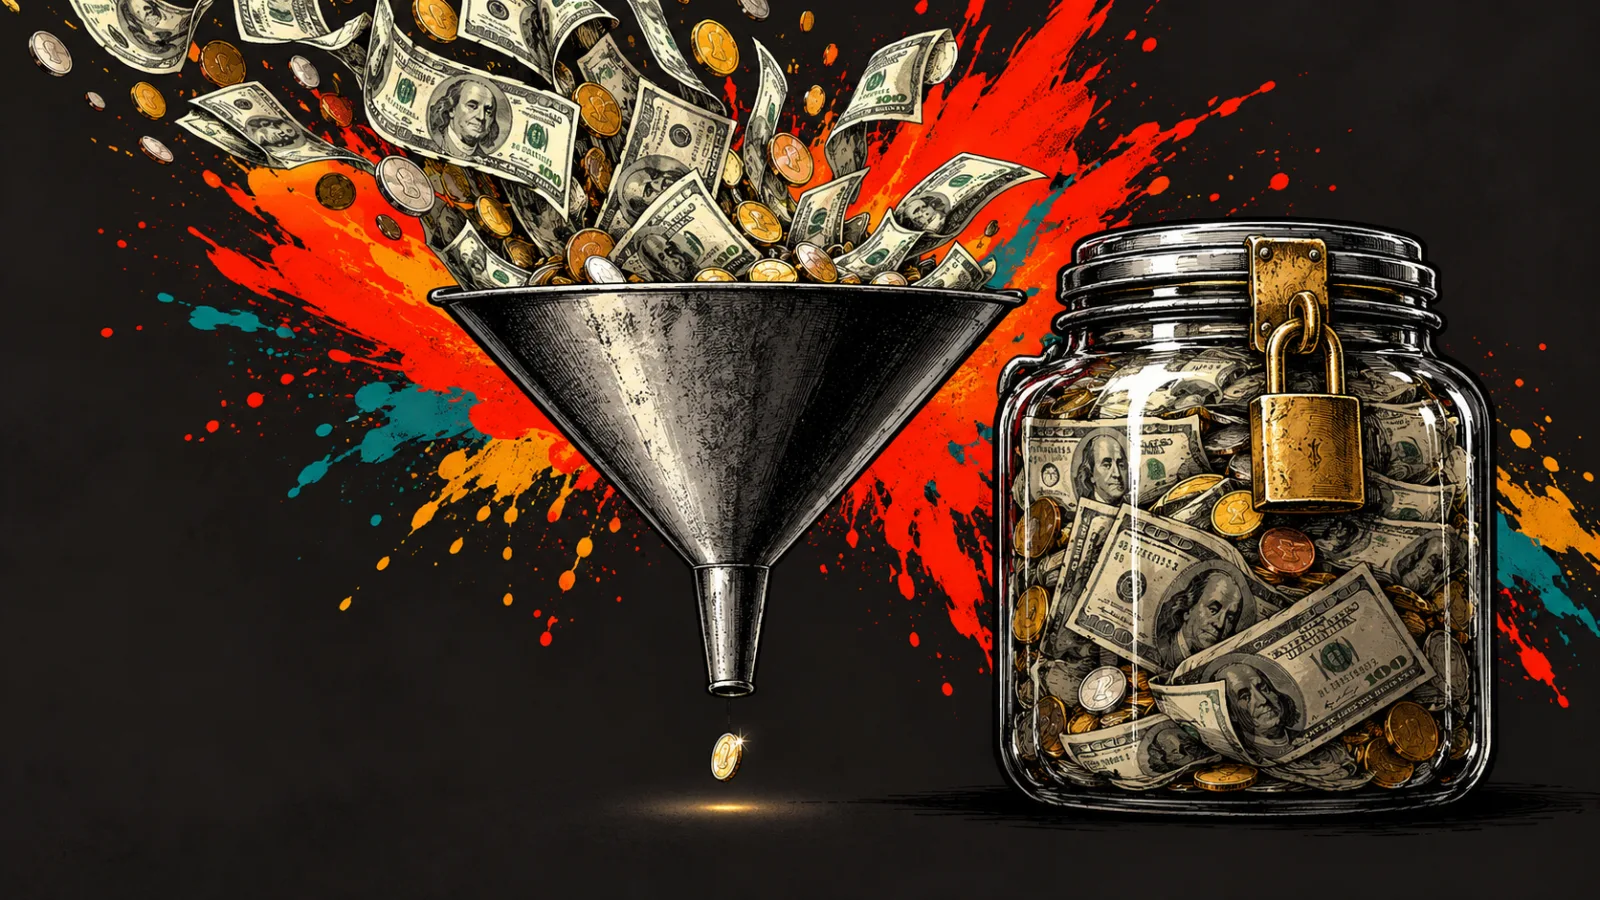
- Its build-up fund, built up over several years, held $220,444 of money it had earned and could not spend. That is 31 times its profit for the year.
- It had no employees, just 12 agents paid by commission, and it described its Denver rivals as "typically run by one or two persons."
- The question for every owner: is your agency a business that could survive you taking two weeks off, or a job you can never leave?
Almost nobody in bail publishes their numbers. Agencies are private, and most are family run. So when one does, it is worth a close look.
Twentyfour/seven Ventures, a Denver company that wrote bail through its subsidiary A Alpha Bail Bonds, filed to register its shares with the Securities and Exchange Commission in January 2013. That meant filing a full annual report with audited accounts, the kind of disclosure a private agency never makes. For 2013 it reported revenue of $512,710.
Its net income was $7,097. The year before, it lost $7,182 on revenue of $475,952, so 2013 was the better of the two.
$7,097
kept from $512,710 of bail revenue by a Denver agency in 2013, according to its own SEC filing. About 1.4 cents on the dollar.
Where half a million went
The filing lists the costs. Commissions to agents took $148,465. The company had twelve agents, all independent contractors paid on the bonds they posted, and $75,775 of those commissions went to affiliates of the company's shareholders.
The surety took $71,463, about 14 percent of revenue. From February 2013 its insurer, Bankers Insurance, took 1.5 percent of the face of every bond. The carrier before it, International Fidelity, took 1.8 percent until it withdrew from Colorado.
Another $113,626 was booked as other costs of sales, up from $41,235 in 2012. The filing does not break that line down, but says its cost of revenues covers bond fees, forfeitures, bounty fees, liability insurance and direct labor and office costs. Recovery fees took $9,780.
Then the overheads: rent of $10,926, other operating costs of $72,082, interest of $6,396 and tax of $1,030.
One line needs a fair caveat. Professional fees came to $71,275, and a public company pays for audits and filings that a private agency would not. Add every dollar of that back and the year leaves about $79,000 before tax, on half a million of revenue. And the chief executive drew no salary at all in 2013.
Here, the shareholders' side earned through commissions to affiliates and interest on their loans to the company, rather than through profit.
The money you earned and cannot touch
Under its surety contract the company had to put 1 percent of the face of every bond it wrote into a build-up fund. At the end of 2013 that fund held $220,444, up $42,429 in a year. Those deposits are not an expense, so the $42,429 came on top of the $7,097 profit, as cash the company could not use. The filing says the money comes back when a court releases the bond, or after a set period, "generally 36 months." It was also holding $82,459 of clients' collateral.
$220,444
sitting in the same agency's build-up fund at the end of 2013: two thirds of everything it owned.
The build-up fund, or BUF, is the cushion that covers forfeitures. Florida and Connecticut make it the agent's money by statute. Florida's law says build-up funds "are the sole property of the agent or agency," may not exceed 40 percent of the premium, and must be paid to the agent within six months after the contract ends and the last open bond is discharged. Connecticut sets the same 40 percent cap and the same six months, after the insurer takes out its losses. Many states have no such rule, so the terms are whatever your contract says.
At the Denver company the fund was $220,444 of $339,515 in total assets. Every dollar of it was earned and could not go toward a second agent, a slow month or a payroll it did not yet have. Our guide to reading your BUF statement covers how to check what is really yours.
If you write bonds on your own property rather than for an insurance company, which some states allow, there is no surety cut and no build-up fund. The rest of the math still applies.
On paper, the agent keeps most of the premium
Officials in three states have described the split the same way. In 2017 California's insurance department worked an example: on a $25,000 bail, the usual 10 percent fee is $2,500. It said the surety typically gets 20 percent of the fee, part of it placed in a "buffer account" against forfeitures, and the agent keeps "$2,000 to $2,250." It also noted that in California agents can rebate the fee down to as little as 2 percent to stay competitive.
In Texas, the sponsor of a 2013 bill put it more simply: the bondsman charges 10 percent of the face value, and the insurance company is paid a premium equal to 1 percent of the face amount. And a Florida Senate staff analysis in 2000 recorded what people representing the industry told it: agents keep 90 to 93 percent of the premium.
Rates and contracts vary by state and by surety, so check your own. The Denver books start from the whole premium: the surety took about 14 percent, commissions and other costs took most of the rest, and another $42,429 went into the fund on top of the $7,097 profit.
How big is an agency, really?
Few regulators publish counts that separate agents from agencies. Washington's does. In September 2026 its Department of Licensing had 148 active bail bond agent licenses, 34 agency licenses and 19 branch licenses. That is about four licensed agents for every agency, or nearer three per office once branches are counted. Washington is one state, and not a big bail state, so treat it as one data point.
The Denver company had no employees: twelve agents on commission and an owner at the center. Its filing described the competition as "numerous other small bail bonding companies in the Denver metropolitan area, typically run by one or two persons, family owned and operated." That was one company's view of its own city, but it will sound familiar to a lot of owners.
Business or job?
A business keeps running when the owner is away. A job stops. Four questions tell you which one you have:
- Who answers at 2am if you are sick for two weeks? If the answer is nobody, new business stops the day you do.
- What did you actually keep last year, after commissions, forfeitures, the surety and the fund? What you wrote is a different number.
- What is in your build-up fund, and when could you get it back? At the Denver company it was the largest thing on the balance sheet.
- What would a buyer pay for? If the answer is "my relationships," you own a job. We wrote about that in the succession problem nobody plans for.
None of this means a small agency is doomed. Plenty have lasted decades. But the margin for a bad year, a lost surety contract or a run of forfeitures can be thinner than the premium suggests, and the cash that would carry you through may be sitting in a fund you cannot reach.
Your turn
How many people work in your agency, counting you? And what would happen if you were off for two weeks? Write to us at info@bailwatcher.com. We will share what the trade tells us, without names.
Sources: Twentyfour/seven Ventures, Inc., Form 10-K for the year ended December 31, 2013, filed with the SEC on April 10, 2014 (revenue, net income and 2012 comparison, cost and expense lines, agents and employees, executive pay, shareholder loans, surety agreements, build-up fund, collateral and total assets, competition); Washington State Department of Licensing, Professional License Counts, bail bonds, September 2026, data.wa.gov; Florida Statutes 648.29 (2025); Connecticut General Statutes 38a-660f; California Department of Insurance, "An Exploration of California's Bail System," overview, January 31, 2017; Texas Senate Research Center, bill analysis of S.B. 1397, 83rd Legislature, 2013, author's statement of intent; Florida Senate staff analysis of CS/SB 1560, March 14, 2000. All read from the source on October 27, 2026.
About the figures: the numbers for Twentyfour/seven Ventures, Inc. and A Alpha Bail Bonds, LLC are quoted from the company's own annual report for 2013, a public filing with the U.S. Securities and Exchange Commission. They describe that one year only, are used to illustrate the economics of a small agency, and are not a comment on the company, its owners or any later business, including under the names it has used since. The Washington figures are license counts from the state's public data, not staff numbers. This article is general information, not legal, tax or financial advice. Spotted an error? Write to info@bailwatcher.com and we will correct it.
Final thoughts
For agency owners: what you write is not what you keep. Count what is left after commissions, forfeitures, the surety and the fund, find out what is in your build-up fund, and ask what would keep the doors open if you were gone for two weeks.
Markets and Surety
READ MORE
You Can't Advertise on Google. Plan as if You Never Will.
by Wade Caldwell · October 19, 2026
California Lost 900 Bail Licenses. Did Anyone Notice?
by Wade Caldwell · October 15, 2026
What a Bail Bond Costs, With Real Numbers
by Wade Caldwell · October 10, 2026